Quick answer
Earthmoving and excavation contractors borrow for excavators, loaders, tippers and floats, for major repairs and attachments, and to carry fuel and operator wages while builders, developers and councils pay on terms. Lenders look at machine utilisation, contracts, the plant register and existing finance, debtor days and the resale market for the gear. Machines usually suit equipment finance; property security helps for larger fleets or contract gaps.
Key points
- Machines are expensive, but they hold resale value lenders understand.
- Utilisation — hours actually worked — matters more than fleet size.
- Fuel and operator wages are paid long before civil and developer invoices.
- Heavy vehicles bring their own registration and compliance costs.
- Common uses
- Excavators, tippers, floats, fuel
- Lenders focus on
- Utilisation, contracts, plant register
- Unsecured options
- Typically $5k – $500k
- Property-secured
- $20k – $5m
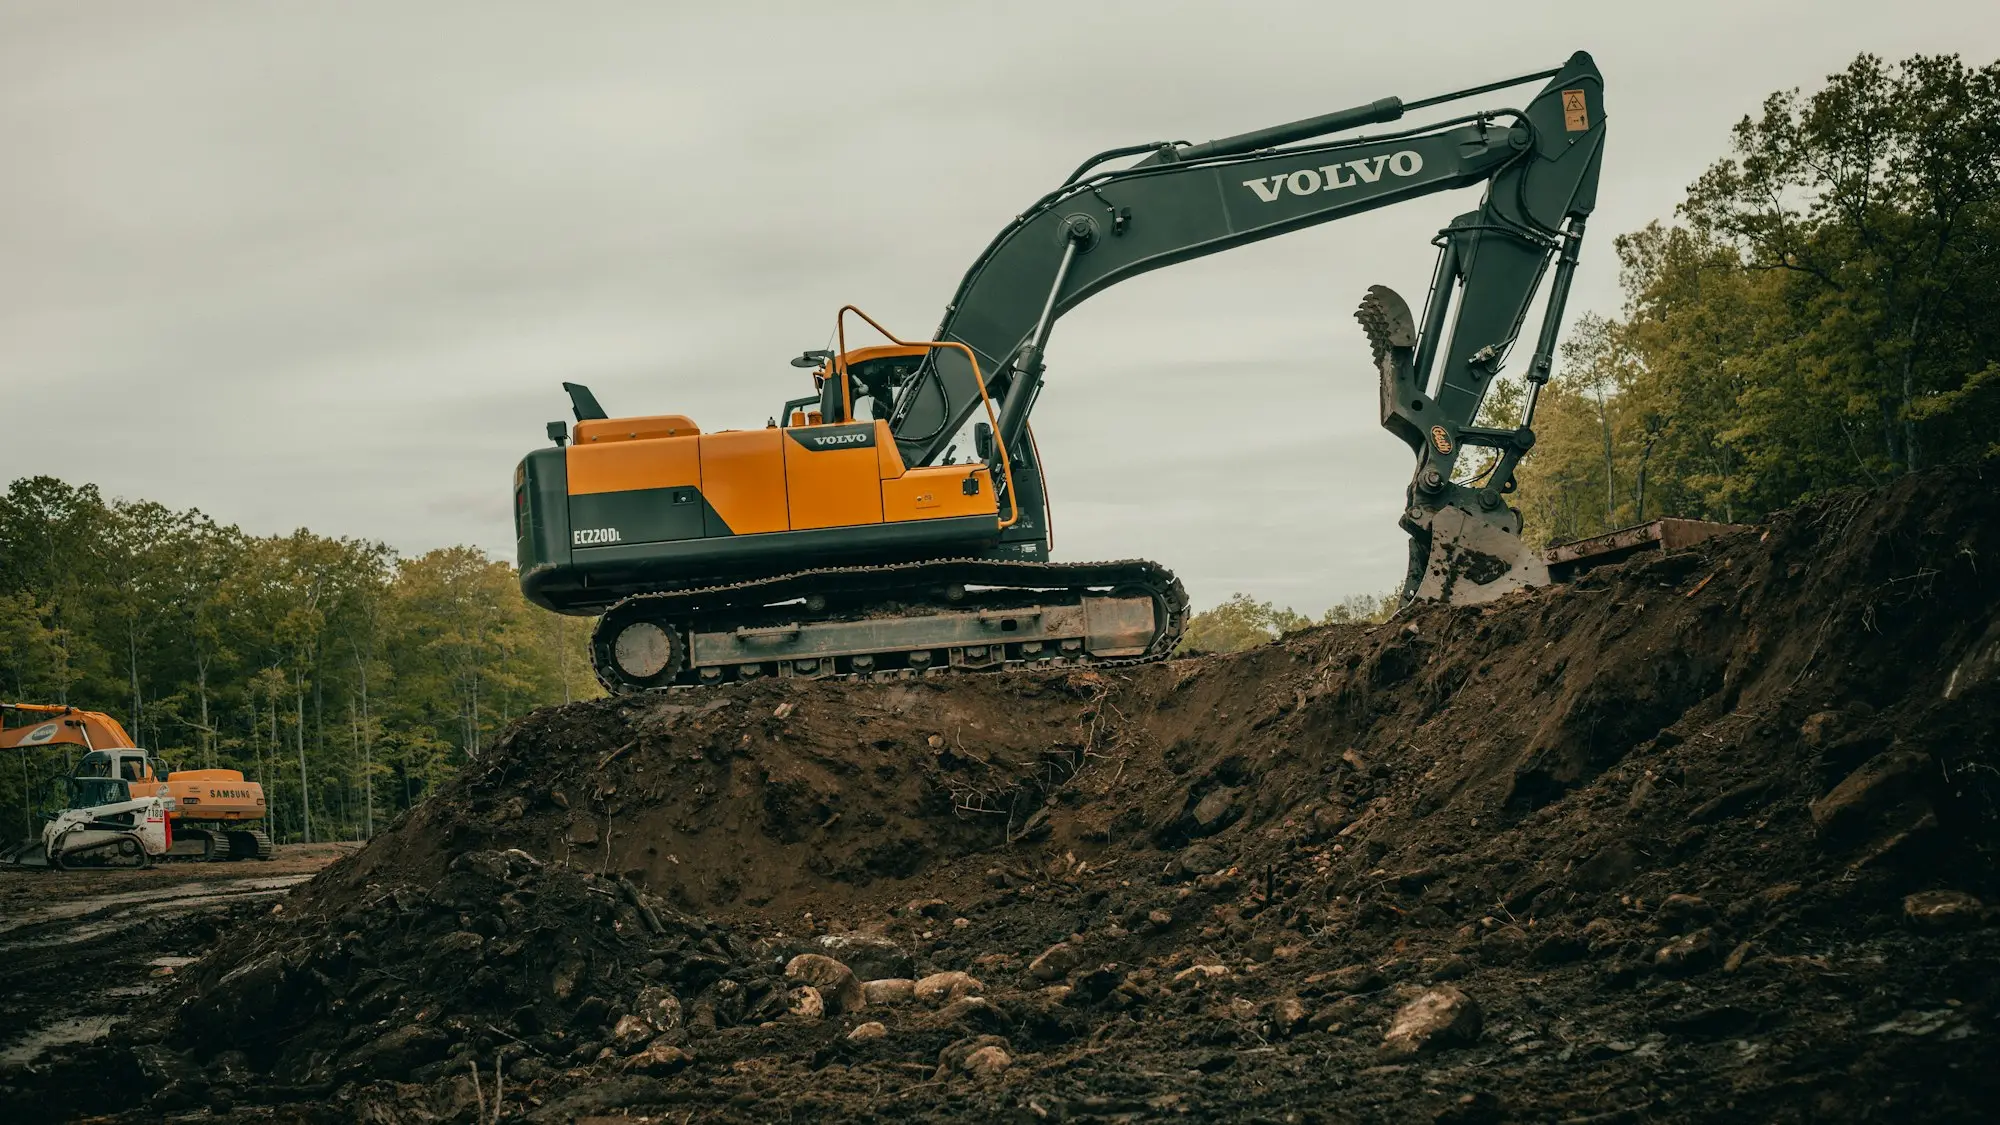
Earthmoving is the most capital-heavy of the building trades. A small operator might own a single mini excavator and a tipper; an established contractor can have a yard full of machines, floats and trucks. An earthmoving business loan is usually about one of three things: adding or replacing plant, fixing plant that has broken down, or carrying the fuel and wages that a big site job needs before the money comes in.
What do earthmoving contractors usually borrow for?
- Machines. Excavators of all sizes, skid steers, loaders, graders, rollers and dozers.
- Trucks and floats. Tippers, truck-and-dog combinations and low loaders to move machines between sites.
- Attachments. Tilt buckets, rock breakers, augers, rippers and grabs.
- Major repairs. Engine rebuilds, undercarriage replacement and hydraulics.
- Working capital. Fuel, operator wages and tip fees while civil, council or developer invoices are outstanding.
- A yard or depot. Land to store the fleet, often bought with property security.
How do lenders look at an earthmoving business?
Utilisation, not just fleet size. A lender wants to know how many hours each machine works. Ten machines that sit idle half the week are a weaker story than four that are booked solid. Bank statements, job sheets and contract schedules all help show it.
The plant register. A full list of machines, their age, hours, condition and any finance owing is one of the most useful documents an earthmover can produce. It shows what the business owns, what it owes and how much equity sits in the yard.
Contracts and clients. Work for volume builders, developers, councils, civil head contractors and private landholders all pays differently. Long payment cycles on civil and developer work mean more working capital is needed.
Heavy vehicle compliance. Trucks and floats over the heavy vehicle threshold come under the National Heavy Vehicle Regulator for safety, access permits and compliance. Lenders expect registration and permits to be current, as overdue compliance can put a truck off the road.
Contractor records. If you put on subcontract operators or hired trucks, expect to report those payments in a taxable payments annual report due 28 August.
Machine down and a site waiting? See if your earthmoving business qualifies — no credit check to ask.
Hire it, buy it, or fix it?
Earthmovers face this choice constantly. A machine you hire most weeks is often cheaper to own. A machine you use once a month is usually better hired. And an older machine with a failed engine may be worth rebuilding if the rest of it is sound.
Lenders appreciate owners who think this way. If you can show what you currently spend on hire, and how owning would cut that cost, the application makes its own case. The same goes for repairs: a quote for the rebuild, alongside the work the machine is booked for, shows the money earns its keep.
Machinery itself usually suits yellow goods finance or equipment finance, secured against the machine. Repairs, fuel and wages fit cash-flow lending. Our guide to plant hire fleet finance covers the angle for businesses that rent machines out.
Which structure fits which earthmoving need?
| Need | Structure that often fits | Why |
|---|---|---|
| New or used excavator, loader | Yellow goods or equipment finance | Machine secures the loan |
| Tipper, truck-and-dog, float | Truck finance | Long-life asset, NHVR-registered |
| Engine or undercarriage rebuild | Cash-flow loan or property-secured | No new asset to secure against |
| Fuel and wages on a big contract | Line of credit | Flexes with claim timing |
| Yard or depot | Property-secured loan | Larger amount, longer term |
| Too many separate machine loans | Business debt refinance | One structure, lower monthly pressure |
A tilt bucket or breaker under the threshold may be claimed in one go via the instant asset write-off, — $20,000 per item for 2025–26. Check the details with your tax agent.
Documents that help
- A full year of business account statements
- Plant register with hours, condition and finance owing
- Contracts, purchase orders or schedule of booked work
- Aged debtors list
- Quotes for machines, attachments or repairs
- Heavy vehicle registration and any permits
- BAS returns and the last set of annual accounts
What worries lenders about earthmoving fleets?
- Machine repayments crowding out fuel and wages.
- Idle machines that cost money but don’t earn.
- One developer or head contractor supplying most of the work.
- Overdue rego or compliance on heavy vehicles.
- Tax owing from a fuel-heavy year, which needs explaining but isn’t always fatal.
Questions a lender will ask an earthmover
- How many machines do you run, and how many hours did each work last month?
- What finance is already owing across the fleet?
- Who are your main clients, and how long do they take to pay?
- How much do you currently spend on hiring in machines?
- Is the money for a new machine, a repair or working capital?
Common misconceptions about earthmoving finance
“The yard full of gear will carry any application.” Equity in machines helps, but repayments still need to be covered by income.
“Newer is always better.” A well-maintained older machine at the right price can be the smarter buy, and lenders recognise that when the numbers are clear.
Illustrative example
Illustrative example: an excavation contractor with three machines and two tippers wins a twelve-month subdivision contract. The work needs a bigger excavator and a float to move machines between stages, about $280k in total, plus roughly $70k to carry fuel and operators until the first monthly claim is paid. Equipment finance covers the excavator and float, secured on the machines themselves. A line of credit sized on banked income covers the working capital, drawn at the start of each month and repaid as claims are paid.
When should an earthmoving business apply?
As soon as a new contract looks likely, or when a machine’s repair bills start to climb. Machines can take time to source, inspect and transport, and lenders need the plant details before approving. Starting early keeps the new gear arriving in time for the job.
Secured or unsecured for an earthmover?
Machines go on asset finance; the running money (fuel, operators, repairs) usually comes from an unsecured facility between $5k and $500k, set by what the bank statements support. When the need is larger, the machines are older or the business is newer, property-secured lending from $20k to $5m can bridge the gap. The concreter guide and landscaping guide cover neighbouring trades.
Ready to get the next machine working for you?
You wouldn’t dig without checking for services first. Treat finance the same way: start with a quick 60-second enquiry, and rest easy knowing there’s no credit check just for enquiring. We won’t send your details out to a dozen lenders, so you won’t be chased by strangers. A real person who understands plant, contracts and wet weeks will review your business and call you. Give us accurate numbers on the form and we’ll aim to bring you a workable structure on the first call.
Frequently asked questions
Can I finance a second-hand excavator?
Yes. Used machines are commonly financed. Lenders look at age, hours, condition, make and the resale market. Very old or very specialised machines may need extra security or a bigger deposit.
What if most of my machines already have finance on them?
That's common in earthmoving. Lenders will look at total repayments against income. If the repayments are crowding out wages and fuel, refinancing several contracts into one structure can sometimes free up cash.
Can I borrow for a major engine or undercarriage repair?
Yes. A cash-flow loan or a property-secured loan can fund a big repair, which is often cheaper than replacing the machine. Lenders want to see that the machine has work waiting once it's fixed.
Do lenders care about wet weather downtime?
They expect it. What they look for is a business that keeps repayments up through wet months, either through cash reserves, a line of credit or work that can continue in the rain.
Can I finance attachments like tilt buckets and rock breakers?
Yes. Attachments are often bundled with the machine or financed separately as equipment. They add earning capacity, which helps the application.