Quick answer
Floor plan finance is a revolving facility that funds a dealer's stock unit by unit. The financier pays for each vehicle, caravan, boat or machine as it arrives, holds a registered security interest over it, and is repaid when that unit sells. Dealers pay ongoing charges while stock sits, face regular audits, and must repay promptly after each sale. It suits licensed dealers holding high-value, serial-numbered stock.
Key points
- Each unit is funded on arrival and repaid when it sells, so the facility revolves with your stock.
- Financiers register their interest on the PPSR, usually as a purchase money security interest that must be in place before delivery.
- Retail buyers from a licensed dealer generally take the goods free of the financier's interest, which is why prompt repayment and audits matter so much.
- Holding costs grow the longer a unit sits, so ageing stock is the dealer's biggest cost risk.
- Selling a unit and not repaying it promptly is the fastest way to lose a facility.
Floor plan finance is a revolving facility that funds a dealer’s stock one unit at a time. The financier pays for each car, caravan, boat or machine as it arrives, registers a security interest over it, and is repaid when that unit sells. In return, the dealer pays holding charges, accepts regular audits and repays promptly after every sale.
It’s the reason a dealership can have a yard full of stock worth many times its own cash. It’s also one of the most tightly managed facilities in business finance. Knowing how it works, and why lenders run it the way they do, makes the difference between a facility that grows with you and one that’s pulled. Floor plans are a specialised branch of inventory finance, built for stock that can be identified unit by unit.
How does floor plan finance work, step by step?
- The facility is approved with an overall limit, rules about what stock can be funded, and how much is advanced per unit.
- A unit is ordered or bought. It might come from a manufacturer, an importer, an auction or a trade-in.
- The financier pays the supplier for that unit, either fully or a set portion, and records it against the facility by serial number.
- The unit sits on the lot. The dealer pays ongoing charges on the amount outstanding, and some facilities require part of the advance to be repaid after a set time (often called curtailment).
- The unit sells. The dealer repays the financier for that unit within the agreed time.
- The limit frees up for the next unit.
Because each unit is funded and repaid on its own, the facility breathes with the dealer’s stock levels. A dealer heading into a busy season can carry more units, then run them down afterwards.
What kinds of dealers use floor plan finance?
The common thread is high-value stock with serial numbers that’s easy to identify and check:
| Dealer type | Typical funded stock | What lenders watch most |
|---|---|---|
| Car and motorcycle dealers | New and used vehicles | Age of stock, used-car valuations, sale-and-repay timing |
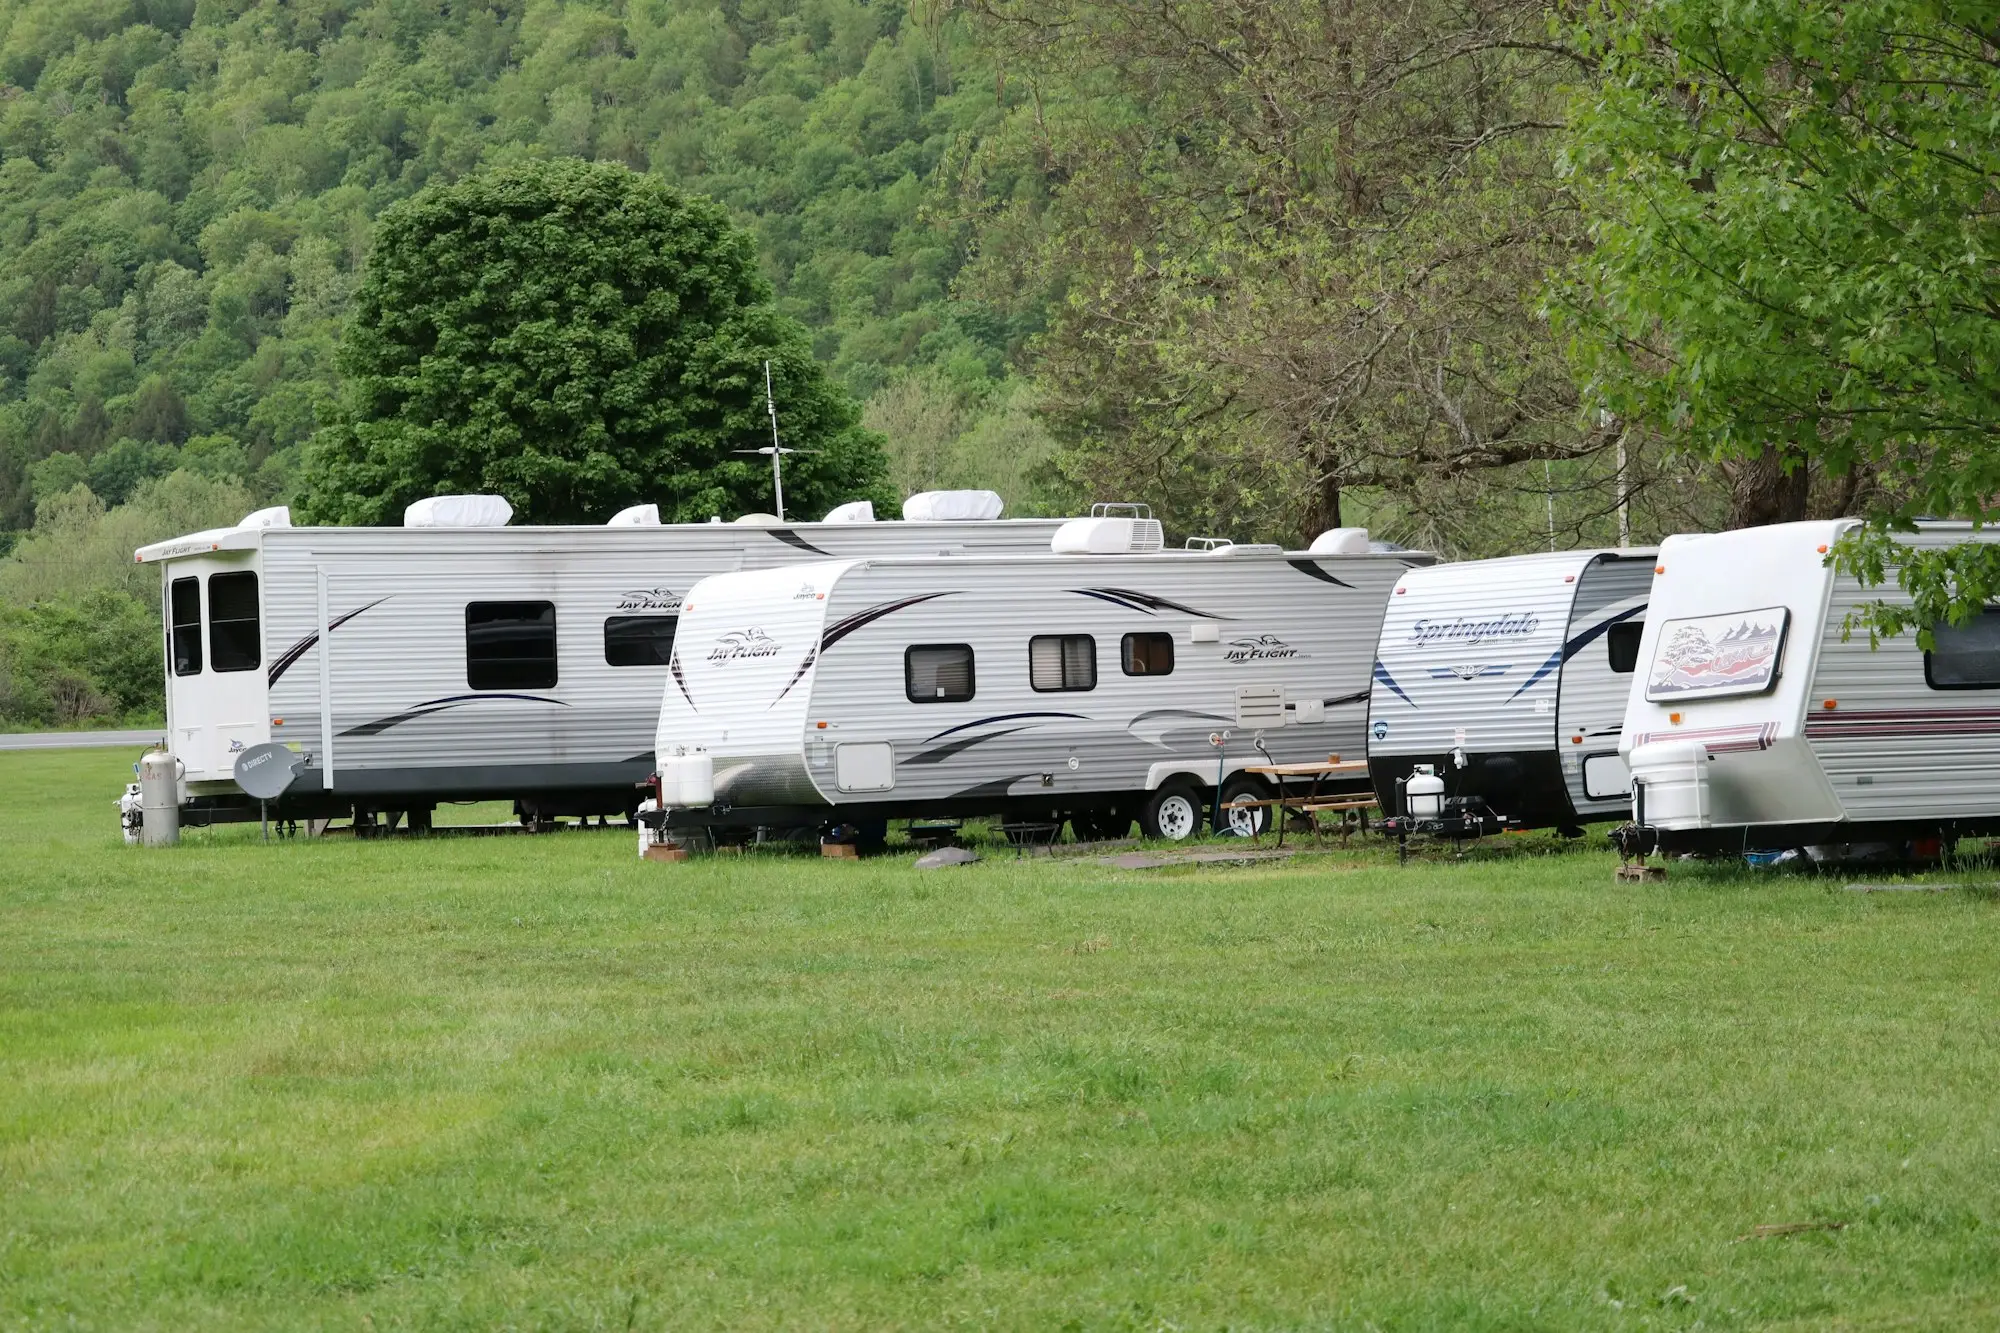
| Caravan and RV dealers | Caravans, campervans, camper trailers | Seasonality, model-year changes |
| Marine dealers | Boats, outboards, trailers | Seasonality, ageing stock |
| Agricultural machinery dealers | Tractors, harvesters, implements | Seasonal demand, regional conditions |
| Earthmoving and equipment dealers | Excavators, loaders, yellow goods | Hours, condition, resale market |
Machinery and equipment dealers often also arrange finance for their buyers. Our pages on agricultural machinery finance and yellow goods finance explain that customer side.
What does the PPSR have to do with floor plan finance?
Almost everything. The PPSR’s guidance for the automotive industry notes that dealers can often borrow against floor stock, and that consignment and finance leasing arrangements are common. It explains that motor vehicles should be registered against their serial number, such as the VIN or chassis number, where known.
Two PPSR rules shape how floor plan financiers behave:
Timing. Financiers who fund stock usually rely on a purchase money security interest, which can rank ahead of earlier registrations over the same goods, such as a general security held by another lender. For inventory, the registration has to be in place before the dealer takes possession. That’s why financiers set up their paperwork before the first unit lands, and why new facilities can’t simply be backdated over stock already on the lot.
Buyer protection. The PPSR’s page on motor vehicle searching and buyer protections explains that a buyer who pays for a serial-numbered vehicle from a licensed dealer generally takes it free of any security interest. That protects your customers, but it means the financier’s security over a unit effectively disappears the moment it’s sold. The only thing protecting the financier then is the dealer repaying promptly. Everything about audits and repayment deadlines flows from that.
What does floor plan finance cost a dealer?
Every facility is priced on its own terms, but the costs usually fall into a few buckets:
- Holding charges on the amount outstanding for each unit, for as long as it sits.
- Curtailment payments, where part of a unit’s advance must be repaid after a set period even if it hasn’t sold.
- Facility and audit fees.
- Insurance on the stock, which financiers require.
The big lesson is that cost is driven by time. A unit that sells in three weeks costs very little to carry. A unit that sits for nine months can eat most of its margin. That’s why stock age is the number floor plan dealers watch most closely, and why our guide to stock turnover applies to dealers as much as anyone.
If ageing units are squeezing your cash, or curtailments are coming due faster than sales, tell us what’s happening in a quick enquiry. Sometimes a separate working capital or property-secured loan can take the pressure off while the stock sells.
What do floor plan financiers check before approving a dealer?
- Dealer licence and history. Most facilities are for licensed dealers with a trading track record.
- Financials and stock records. Sales volumes, margins, stock ageing and how quickly units turn.
- Systems. Can the dealer track every unit by serial number and produce reports the financier can reconcile?
- Premises and security. Where stock is kept, how it’s secured and insured.
- Directors and guarantees. Personal guarantees from directors are common.
- Existing security. Whether another lender already holds a general security over the business and how priority will be handled.
Once the facility is running, audits become part of life. The easiest audits are the ones where nothing needs explaining: every funded unit is on the lot or shown as sold and repaid, demonstrator and loan vehicles are logged with their location, and units at a show, on a test drive or out for repair have a paper trail. Dealers who keep a daily reconciliation between their dealer management system and the financier’s stock list rarely have trouble. Dealers who reconcile once a month tend to discover problems at the same time as the auditor does, which is the worst possible moment.
It also pays to treat repayment timing as non-negotiable. Even a well-run dealership can be tempted to hold a sale’s proceeds for a few days to cover wages or a supplier. To a financier, that looks exactly like the start of selling out of trust.
Illustrative example: a regional caravan dealer
Illustrative only. A regional caravan dealer has a floor plan limit of $2m, enough for about 30 vans. Heading into spring, it fills the yard. A wet summer slows sales, and by autumn eight vans have been on the plan for more than six months, with curtailment payments falling due on each.
Rather than discount heavily into a slow market, the dealer takes a short-term business loan secured on its commercial premises to cover the curtailments and holding costs through winter. The aged vans sell steadily the following spring at sensible prices. The floor plan stays in good standing because every sale is repaid on time.
When does a dealer need funding beyond the floor plan?
A floor plan funds stock, not everything else a dealership needs. Dealers often use other finance for:
- Curtailment and holding cost pressure when stock ages.
- Workshop and service equipment, through equipment or vehicle finance.
- Premises improvements or a new yard.
- Used stock the floor plan won’t fund, such as older trade-ins.
- Tax and BAS payments in a slow quarter.
Unsecured options for trading businesses typically run from $5k to $500k based on turnover and bank statements, and property-secured business loans from $20k to $5m. The secured or unsecured tool shows which way you’re likely to lean, and our guide to slow-moving stock covers clearing aged units.
Running a dealership? See where you stand
Dealers juggle more moving parts than almost any other business: stock arriving, units ageing, curtailments, customers’ finance and the seasons all at once. If one of those is putting pressure on cash, a conversation with someone who understands floor plans is a good first step.
It’s a short form, about 60 seconds, and there’s no credit check when you first enquire. We don’t push your details out to multiple lenders, so there’s no barrage of calls. A real person looks at your dealership’s situation and rings you. Please answer accurately, particularly stock levels and what’s due, so we can match the right option first time.
Frequently asked questions
Who uses floor plan finance?
Mainly dealers of high-value, serial-numbered goods: new and used cars, motorcycles, caravans and campervans, boats, agricultural machinery and earthmoving equipment. Some larger equipment and appliance retailers use similar facilities.
What's an audit in floor plan finance?
A check, often unannounced, where the financier or its agent confirms every funded unit is on the lot, in the condition expected, or has been sold and repaid. Regular audits are a normal part of the facility.
What does 'sold out of trust' mean?
It describes a dealer selling a financed unit and not repaying the financier within the agreed time. Because the buyer generally takes the unit free of the financier's interest, the financier has lost its security. It's treated as a serious breach and can lead to the facility being cancelled.
Can a used vehicle dealer get floor plan finance?
Yes. Used stock is often funded too, though the amount advanced per unit may be lower and based on a conservative valuation, and limits may apply to how long older stock stays on the plan.
Is there an alternative if I can't get a floor plan?
Smaller dealers sometimes fund stock through a business line of credit, a working capital loan or a property-secured loan. These avoid unit-by-unit audits but don't scale as easily as stock numbers grow.